A casual chat with a niece who had just turned 12 went sideways for one millennial aunt, and she took it straight to TikTok. In a TikTok video posted under the handle @theratchetchristian, she says the girl told her millennials had everything and ruined the economy. The niece added that she learned it in school.
The aunt calls the idea ‘the ultimate gaslight of the century’ and points at boomers and Gen X instead. She argues that millennials inherited a recession and responded by having a good time anyway.
The video cannot establish what any classroom teaches. The claim arrives secondhand through a 12-year-old’s memory, so the school, the grade and the lesson all remain unverified. The economic record is public, though, and it does not favor the niece’s version.
Millennials were between 12 and 27 when the system cracked
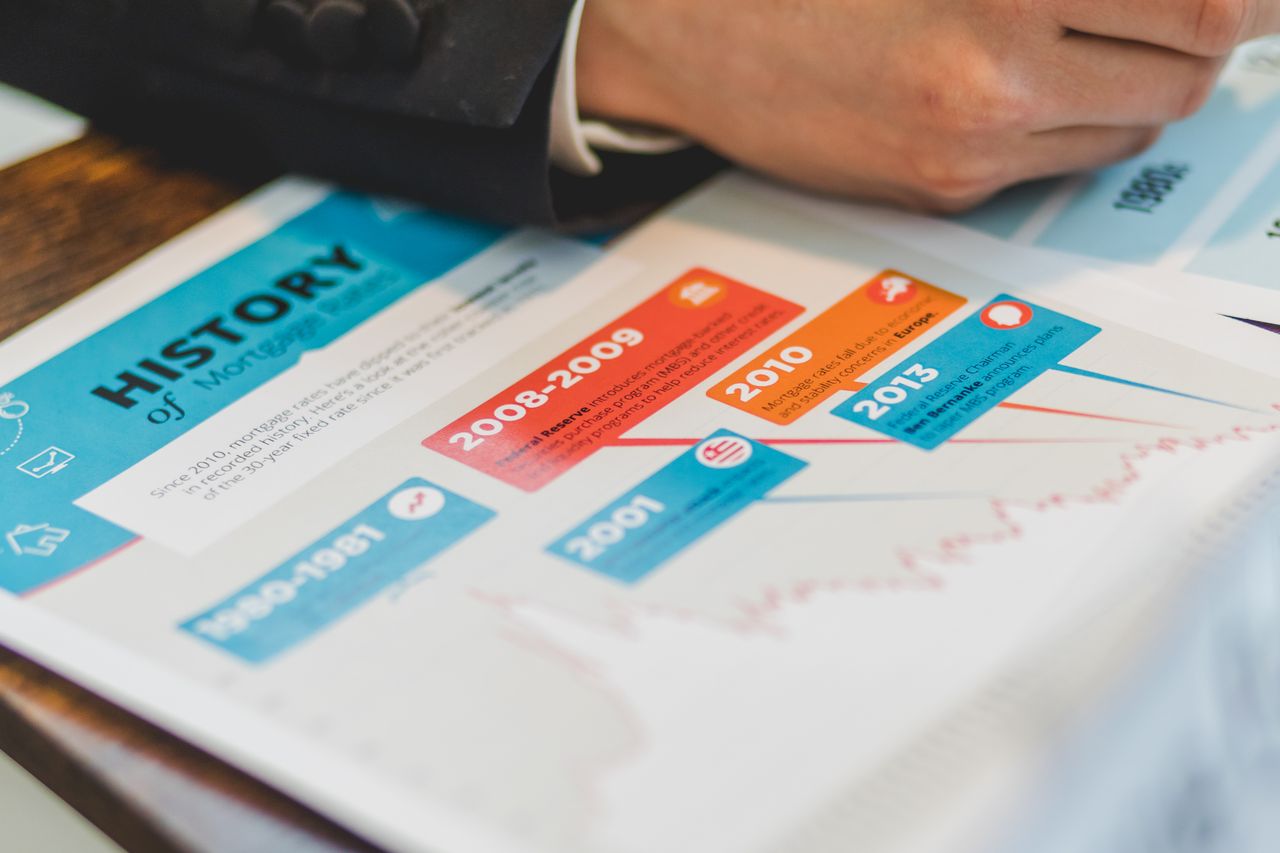
Pew Research Center’s generational cutoffs put millennials at birth years 1981 through 1996. Subtract from 2008 and the generation spans roughly age 12 to age 27 when the housing market buckled.
The youngest were the niece’s age today. A 12-year-old has never signed a mortgage, rated a bond or approved a lending standard. Even the oldest millennials were fresh out of school and nowhere near a boardroom.
Congress blamed institutions, and no generation took the fall
The Financial Crisis Inquiry Commission, created by Congress in 2009, released its final report in January 2011 and called the meltdown avoidable. Its conclusions cite widespread failures in financial regulation, dramatic breakdowns in corporate governance and excessive borrowing by households and Wall Street.
Republican members dissented, and they accused the majority of seeking only facts that fit its starting assumptions. Even the dissent argued over which institutions and policies failed, with no one arguing over which birth cohort did.
The aunt’s own target is just as blunt, since the report names decisions and institutions rather than a birth cohort. Blaming boomers and Gen X wholesale is the same lazy move as blaming millennials, aimed in the other direction.
Entering work in the aftermath left a measurable mark
Researchers at the Stanford Center on Poverty and Inequality compared generations at the same age, and their findings in Pathways magazine point one way. Millennials at every education level were more likely than the three prior generations to be unemployed at 25. The researchers attribute the gap to the Great Recession.
Center director David Grusky calls the pattern the millennial problem. Nothing in that research supports the idea that millennials hoarded jobs, which makes the niece’s version of events hard to square with the data.
Student debt doubled while starting wealth shrank
Pew’s 2019 portrait of millennial life lays out the balance sheet. The share of young-adult households carrying student debt doubled between 1998 and 2016. The median amount owed reached $19,000 for millennials, against $12,800 for Gen X borrowers at the same stage of life.
Net worth tells the same story. Millennial households headed by adults aged 20 to 35 had a median of about $12,500 in 2016, while boomer households that age in 1983 held about $20,700. Starting a household with less cushion and more debt is a poor description of a generation that supposedly took everything.
The typical first-time buyer is now 40
In 1981 the median first-time homebuyer was 29. The National Association of Realtors reported in November 2025 that the figure had climbed to a record 40, and that first-timers had fallen to a record low of 21% of buyers. NAR’s own release puts repeat buyers at a median age of 62.
Before 2008, first-time buyers made up roughly 40% of purchases, according to NAR. The group has also estimated that waiting until 40 instead of 30 can cost roughly $150,000 in equity on a typical starter home.
The generation accused of ruining the housing market is the one the market has been slowest to let in. Blaming people for a market they struggle to enter is a hard case to make.
Boomers hold more than half of household wealth
Data from the Federal Reserve’s Distributional Financial Accounts show boomers holding 52.5% of U.S. household net worth in the second quarter of 2026, or $97.4 trillion. Gen X held 25.7%. Millennials held 11.2%, a figure that includes Gen Z, because the Fed’s group covers everyone born in 1981 or later.
Skeptics have a fair point here. Wealth builds with age, so older generations will always hold more, and a raw snapshot flatters the argument. Age-matched comparisons are the fairer test, and Pew’s 1983 versus 2016 net worth figures are exactly that kind of test.
The recession soundtrack arrived late, but the instinct was real
The aunt says millennials took the lemons and made lemonade, crediting the recession for the music they gave everyone else. Her timeline runs loose, since 2016 sits eight years after the crash. Her point about a generation coping with humor and a good time when the ground moved is still easy to recognize.
The sharper question is where a 12-year-old picked up a verdict that the record does not support. Maybe a teacher said it, maybe a feed did, maybe a relative at dinner. The aunt’s advice amounts to handing kids the dates and the data before handing them a villain.