Retirement should feel like freedom, not a slow leak in the bank account. The problem is that money wasted in retirement rarely arrives as one dramatic mistake. It usually shows up as a few extra subscriptions, one adult child who still needs “temporary” help, a house that costs too much to maintain, a car that barely moves, and benefits claimed before the numbers have been tested.
We have to treat retirement money differently from working years’ money because the recovery window is shorter. The U.S. life expectancyat age 65 was 19.7 more years in 2024, which means many retirees are planning for a retirement that can easily stretch two decades or longer. That is wonderful news for life, family, and grandkids, but it also means every recurring expense deserves a second look.
Claiming Social Security Too Early Without Running the Numbers
Taking Social Security at 62 can feel smart because the benefits start sooner. The trap is that early claiming permanently reduces the monthly benefit, and for people born in 1960 or later, claiming at 62 can reduce a full retirement benefit by about 30%. That smaller check follows a retiree through every grocery bill, rent increase, utility hike, and later medical copay.
We should not treat “eligible” as the same thing as “optimal.” A retiree in poor health or without savings may need to claim early, but someone with flexibility should compare age 62, the full retirement age, and age 70 before making a decision. Social Security delayed retirement credits can increase benefits after full retirement age, and the increase stops at age 70.
Keeping a Large Home That No Longer Fits the Life

A paid-off house can still be expensive. Property taxes, insurance, repairs, utilities, lawn care, snow removal, roof work, pest control, plumbing, and unused rooms all keep charging rent against retirement income. A large home may feel like security, but it can quietly become a luxury asset disguised as a family memory.
We should look at the house as both a shelter and a monthly operating cost. If half the rooms stay empty, the stairs feel harder, and repairs keep appearing, downsizing may protect cash flow without destroying comfort. A smaller home, condo, senior-friendly apartment, or moving closer to family can reduce expenses and make daily life easier.
Missing Medicare Deadlines and Paying Penalties for Life
Medicare mistakes are painful because they can follow retirees for years. The Initial Enrollment Period generally lasts seven months, beginning three months before the month a person turns 65 and ending three months after that month. Missing the window can mean delayed coverage, gaps in protection, and permanent late penalties unless the retiree qualifies for a Special Enrollment Period.
The Part B penalty is especially costly. Medicare says the monthly premium can rise by 10% for each full 12-month period someone could have signed up but did not, and that penalty usually lasts as long as the person has Part B. In 2026, the standard Part B premium is $202.90, so even one avoidable mistake can become a recurring monthly drain.
Carrying High-Interest Debt Into Retirement
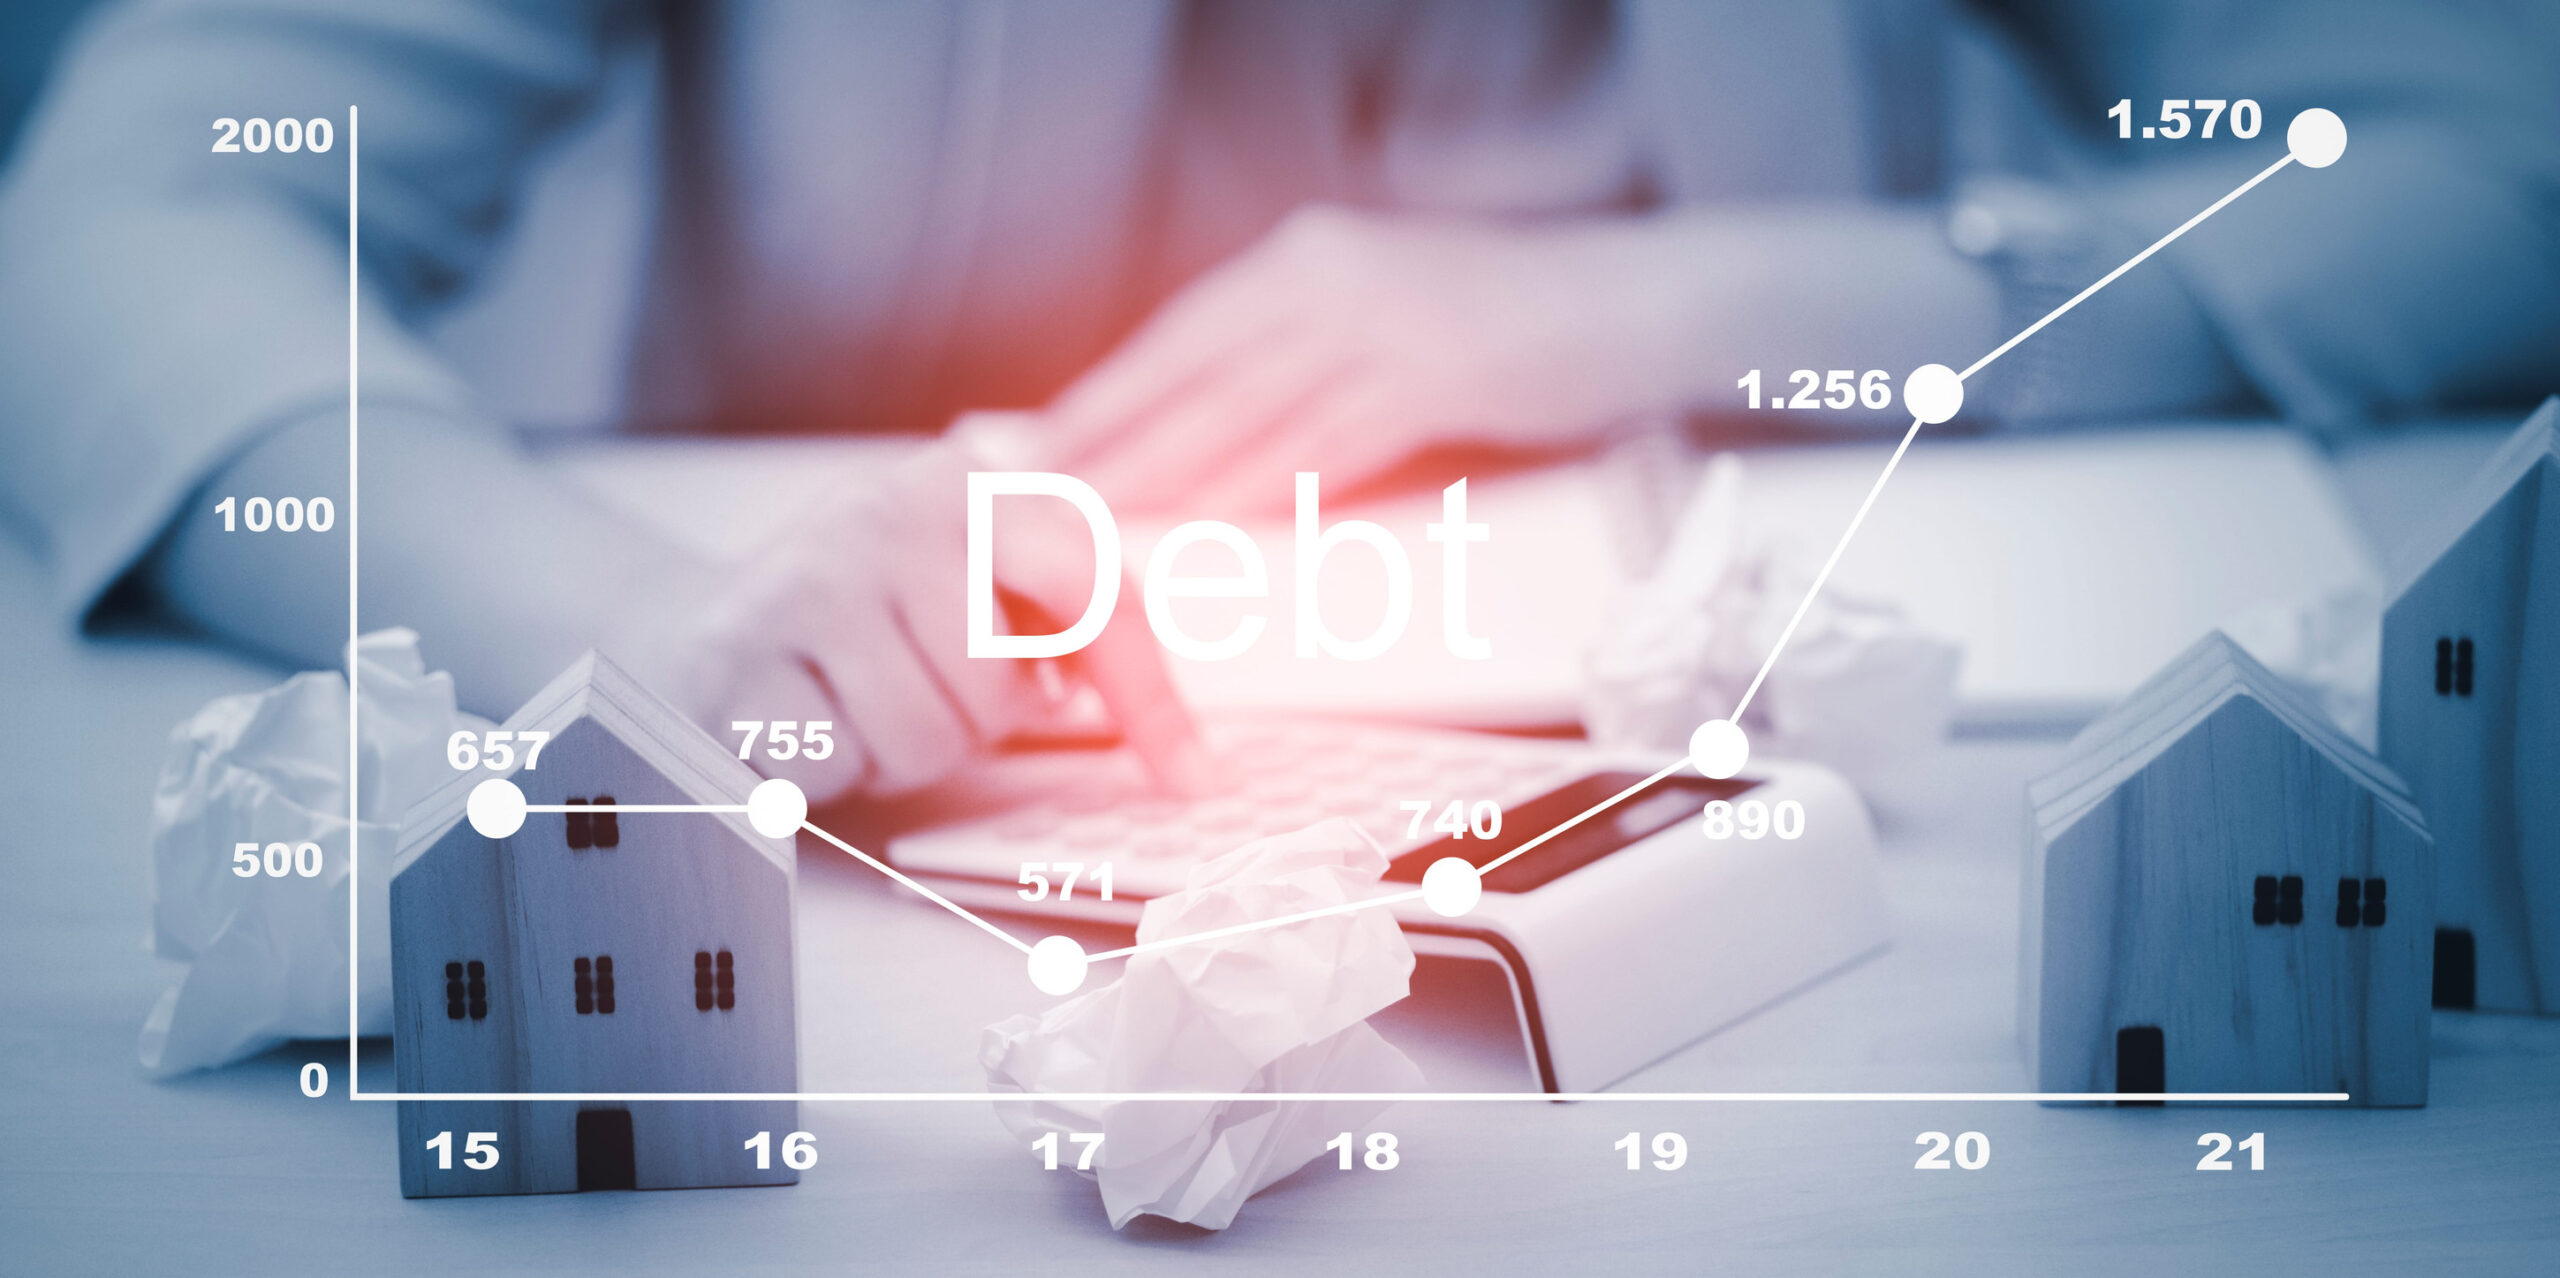
Credit card debt is expensive at any age, but it becomes brutal on a fixed income. Interest charges eat money without improving comfort, health, safety, or quality of life. A retiree who keeps carrying balances may end up paying for last year’s groceries, furniture, trips, or gifts long after the joy has faded.
We should attack high-interest debt before lifestyle upgrades. If retirement has already started, the goal should be a disciplined payoff plan rather than scattered payments that barely touch the principal. Debt consolidation, balance transfer offers, nonprofit credit counseling, or a temporary spending freeze can help, but the key is refusing to normalize interest as a permanent retirement bill.
Letting Subscriptions and Memberships Renew Forever
Small automatic charges are the mosquitoes of retirement spending. One streaming service, one cloud storage plan, one gym membership, one meal app, one magazine, one identity protection plan, and one unused club fee may not look dangerous on their own. Together, they can drain hundreds or thousands of dollars a year.
We should review every recurring charge at least twice a year. Any service that has not been used in 60 days should earn its place again. Retirement budgets do not collapse solely because of big purchases; they often weaken because nobody questions the small charges that go unnoticed.
Giving to Every Charity Request Without Verification
Generosity is beautiful; guilt-driven giving is expensive. Retirees often receive mailers, calls, texts, emails, and social media appeals that make every cause sound urgent. Some are legitimate, but others are designed to pressure older adults into quick donations.
The FTC maintains consumer guidance on scams targeting older adults, including shopping, donating, health, funerals, and other areas that can affect retirees. We should verify charities before giving, avoid donating under pressure, and refuse payment methods that feel unusual or rushed.
Overspending on Travel Because Every Trip Feels Earned
Retirement travel can be one of life’s great rewards. The waste begins when every trip becomes a premium trip, every room becomes an upgrade, and every destination is chosen for fantasy rather than budget. A few luxury vacations can do more damage than years of careful coupon clipping can repair.
We should travel with intention rather than impulse. Off-season dates, longer stays in cheaper destinations, home exchanges, senior fares, points, travel alerts, and slower itineraries can stretch the same budget. The goal is not to stop traveling; the goal is to stop paying peak prices for memories that could cost far less.
Refusing Senior Discounts Out of Pride
Some retirees leave money on the table because they do not want to ask for senior pricing. That pride can get expensive across restaurants, pharmacies, hotels, museums, phone plans, grocery stores, transit systems, insurance programs, and travel services. A 10% discount may seem small, but cumulative discounts can add up to real annual savings.
We should ask politely and make it normal. Retirement is not the season for proving youthfulness at full price. If a discount exists, taking it is not cheap; it is efficient.
Ignoring Technology That Can Lower Everyday Costs
Avoiding technology can cost retirees more than they realize. Price comparison tools, banking alerts, pharmacy apps, coupon extensions, budgeting dashboards, gas-price apps, telehealth portals, library apps, and digital statements can all reduce waste. Refusing every tool because “the old way works” can mean paying more for the same product.
We should choose simple, safe tools and ignore the rest. A retiree does not need to become a tech expert. Even basic alerts for bank balances, credit card charges, prescription refills, bill due dates, and unusual activity can protect both money and peace of mind.
Eating Out and Ordering Delivery Too Often
Dining out is enjoyable, and retirement should include pleasure. The problem starts when restaurants, coffee runs, takeout, and delivery apps replace ordinary home meals by default. Delivery fees, service charges, tips, markups, and impulse add-ons can turn a simple dinner into a budget bruise.
We should make restaurant spending visible. A monthly dining limit keeps enjoyment within bounds. Cooking at home most days, meeting friends for lunch instead of dinner, splitting portions, using gift cards wisely, and reserving restaurants for meaningful outings can preserve both money and social life.
Conclusion
Retirees waste money most often when old habits continue into a new financial season. A large home, two cars, automatic subscriptions, adult-child support, early Social Security, brand-name prescriptions, and unplanned travel can all feel harmless until they combine into a serious cash-flow problem.
We do not need a joyless retirement to protect wealth. We need a deliberate one. The strongest retirement budget leaves room for family, comfort, travel, hobbies, generosity, and health while cutting the expenses that no longer serve the life we are actually living.