Money rarely stops growing because of one dramatic mistake. More often, it gets trapped by small habits that feel harmless in the moment: an unpaid credit card balance, a lazy savings account, a vague budget, a delayed investment plan, or a financial goal that exists only in the mind. By April 2026, the U.S. personal saving rate had fallen to 2.6%, showing how easily income can pass through households without becoming lasting wealth.
We grow money when every dollar has a job before temptation finds it. Savings need direction, debt needs boundaries, and investments need time. If we want our money to grow faster, we must stop treating money management as a monthly mood and start treating it as a system.
Poor Financial Planning Leaves Money Without Direction
Money grows slowly when we do not tell it where to go. A paycheck can look strong on paper, but without a written plan, it disappears into bills, groceries, subscriptions, impulse buys, and small “I deserve this” moments. We may feel busy, responsible, and even careful, yet still end the month wondering why the account balance looks almost the same.
A strong financial plan begins with priorities. We should know how much goes to essentials, how much to debt, how much to emergency savings, and how much to long-term investing. The goal is not to punish ourselves with a lifeless budget, but to stop every new expense from quietly outranking our future.
Weak Savings Accounts Let Inflation Eat Your Money
Leaving too much money in a basic savings account can feel safe, but safety without growth creates a hidden problem. In May 2026, the national savings deposit rate was only 0.38%, which means many savers were earning very little on idle cash. At the same time, the PCE price index rose 3.8% year over year in April 2026, meaning prices were rising much faster than ordinary savings interest rates.
That gap matters. If our cash earns less than inflation, we may have the same number of dollars but less buying power. We still need liquid savings for emergencies, but money meant for long-term goals should usually work harder than a low-yield account allows.
Credit Card Interest Cancels Out Financial Progress
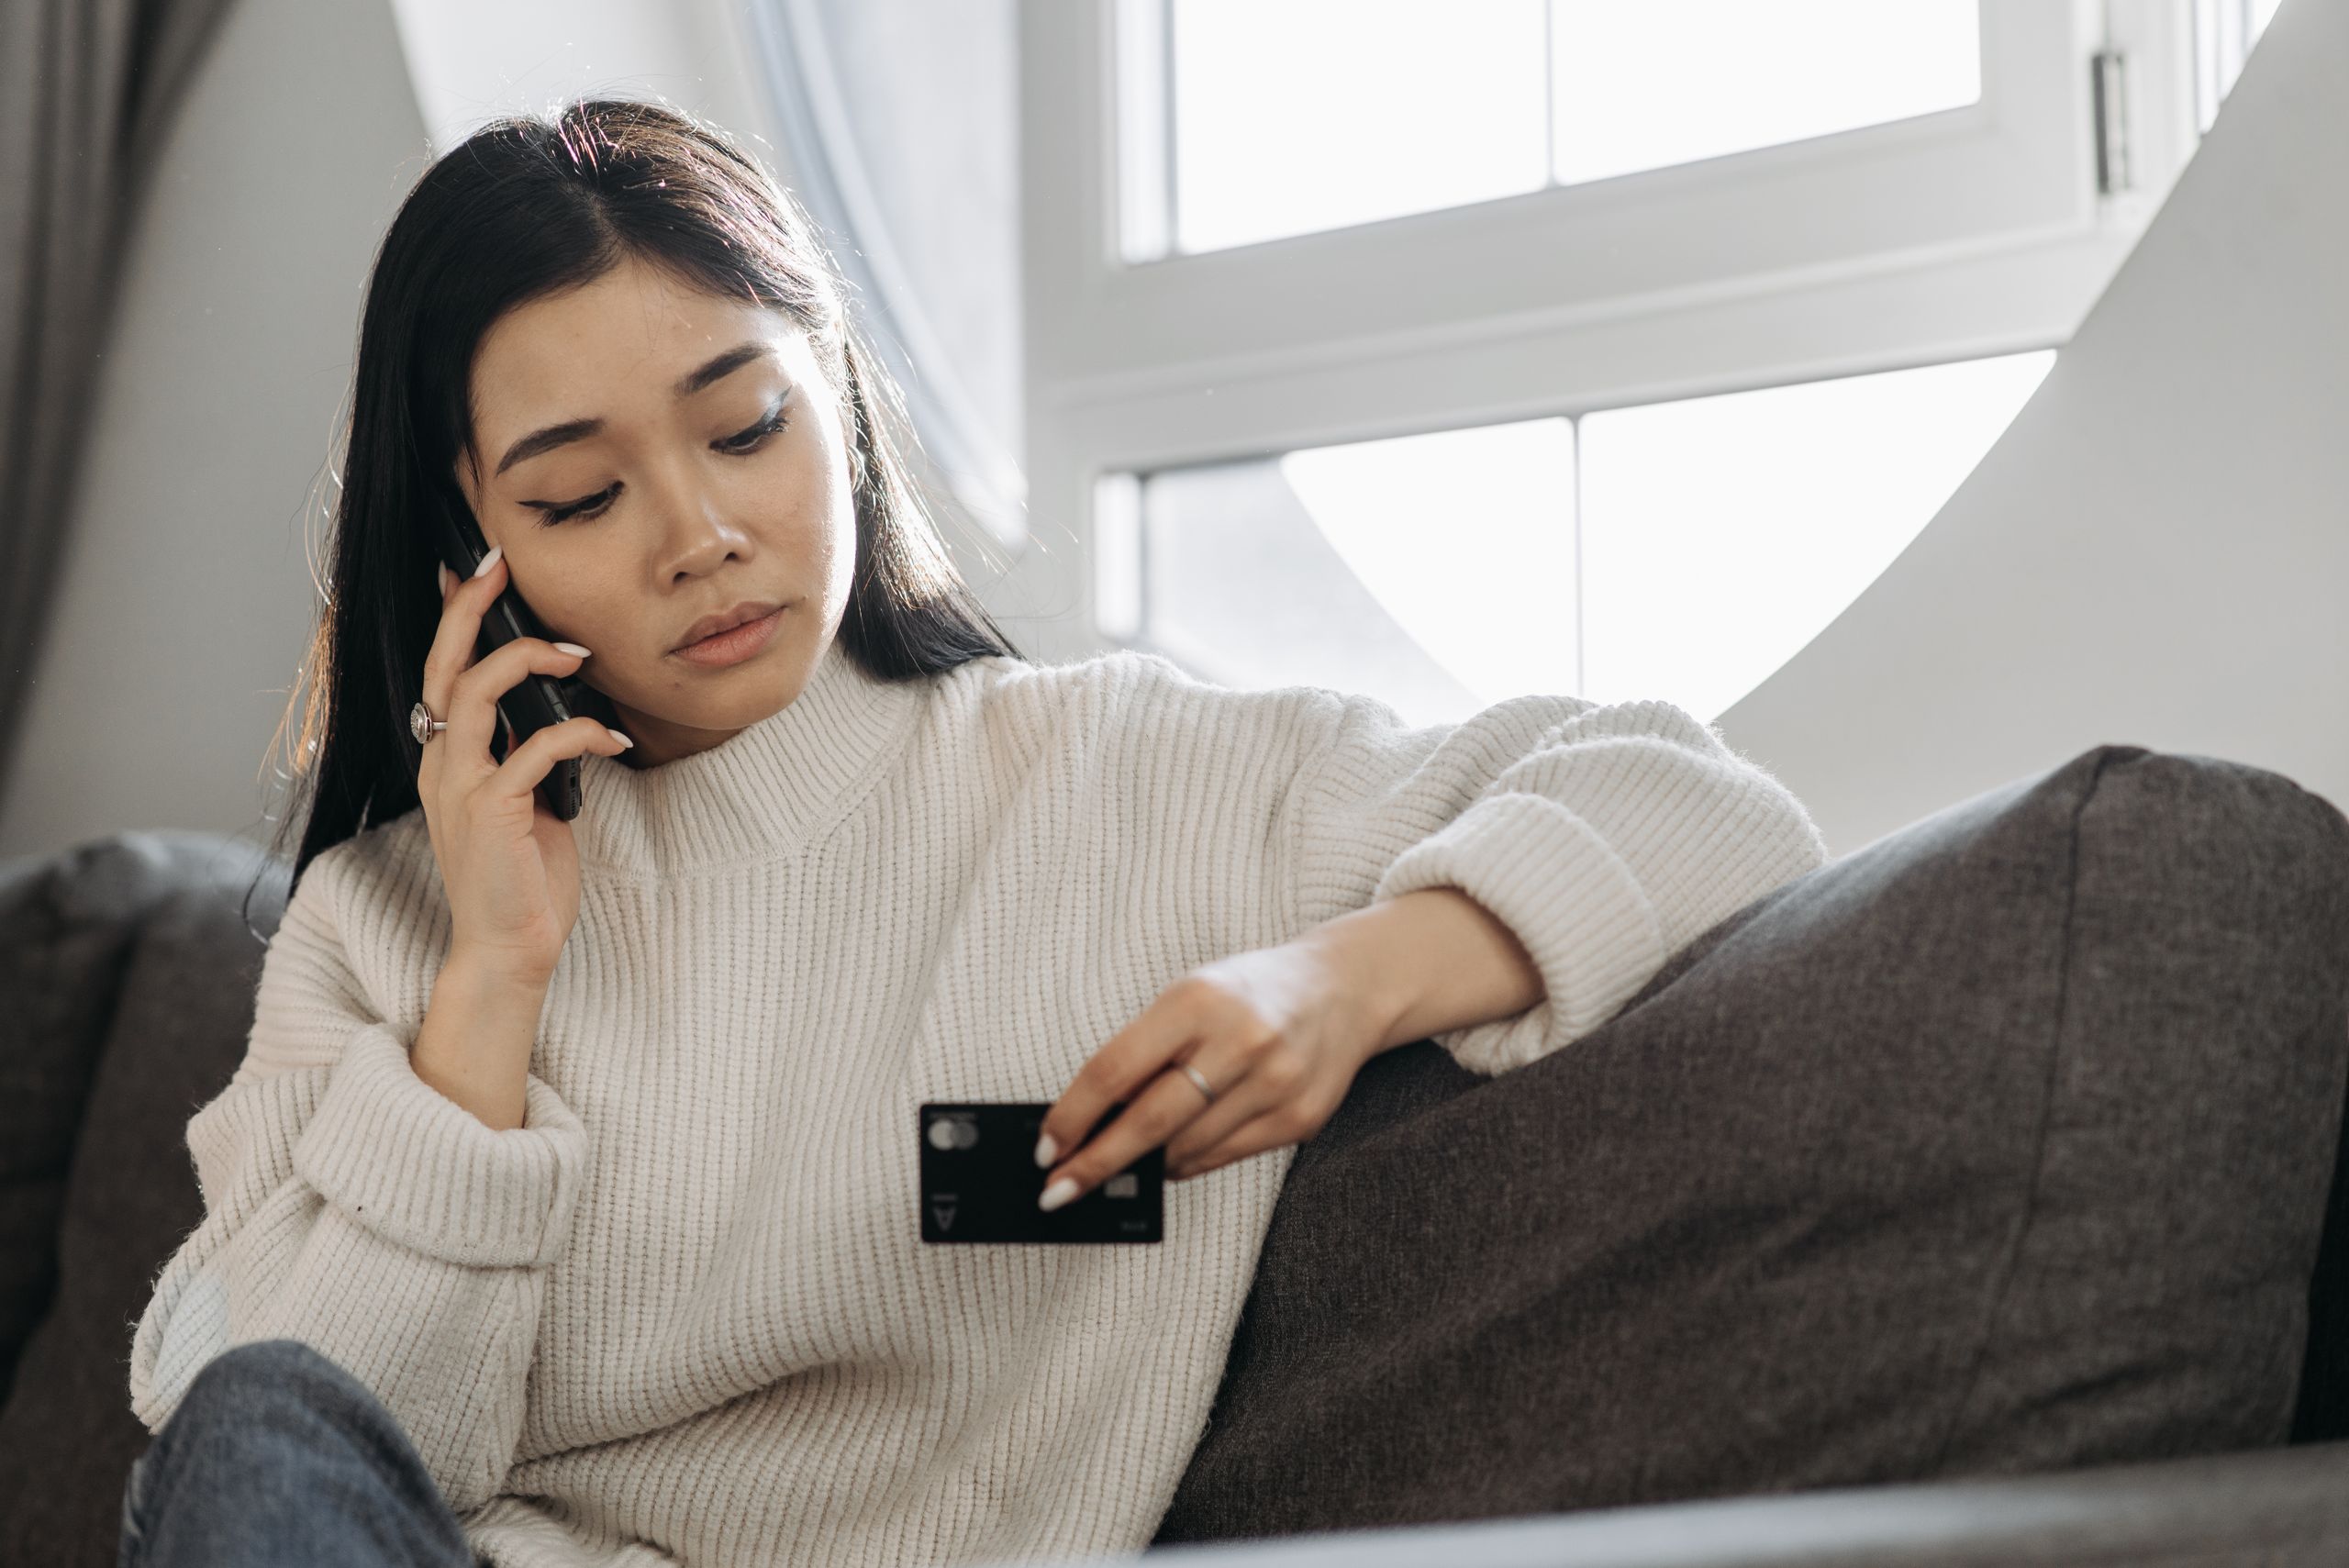
Credit card debt is one of the fastest ways to drain future wealth. In February 2026, the commercial bank interest rate on credit card plans was 21.00%, making unpaid balances expensive even before late fees or penalty rates were applied. A household can invest carefully, save consistently, and still lose ground if revolving debt grows faster than those gains.
We should treat credit card interest as a financial leak, not a normal bill. Paying only the minimum keeps the balance alive and allows interest to keep feeding on tomorrow’s income. A smarter plan is to aggressively reduce high-interest balances, avoid new unpaid charges, and use credit cards as payment tools rather than as a source of emergency income.
No Clear Money Goals Makes Saving Feel Optional
Saving becomes easier when the target is specific. “We need to save more” is too vague to fight impulse spending, but “we need $5,000 for an emergency fund by December” gives every dollar a purpose. The clearer the goal, the easier it becomes to measure progress, cut waste, and say no to spending that does not fit the plan.
Good money goals should include an amount, a deadline, and a reason. We may be saving for a house deposit, a business, a retirement account, a child’s education, or freedom from debt. Once the goal becomes visible, money management stops feeling like restriction and starts feeling like movement.
Unrealistic Return Expectations Lead To Bad Decisions
Many people lose patience because they expect money to grow too quickly. They jump from one investment idea to another, chase viral tips, sell during temporary dips, or take risks they do not understand. The problem is not ambition; the problem is expecting long-term wealth from short-term excitement.
Compound growth needs time, consistency, and reinvested earnings. Investor.gov’s compound interest tool is built around the key inputs that shape growth: initial investment, monthly contributions, time, and estimated return. We build wealth more reliably when we focus on regular contributions and long-term horizons instead of gambling on sudden breakthroughs.
Avoiding All Risk Can Keep Wealth Stuck
Some people lose money by taking reckless risks, but others lose buying power by avoiding risk completely. If every dollar sits in cash for years, inflation can weaken its value. The goal is not to throw money into dangerous investments; it is to match the right level of risk to the right timeline.
Money needed soon should remain stable and accessible. Money meant for years ahead can usually tolerate more movement in exchange for stronger growth potential. Diversification helps manage risk by spreading investments across and within asset classes, rather than relying on a single stock, sector, or lucky guess.
Spending Without Limits Keeps Income From Becoming Wealth
A rising income does not automatically create wealth. Many people earn more and simply upgrade every part of their lifestyle: better restaurants, newer phones, bigger apartments, richer vacations, and more subscriptions. The money looks bigger, but the gap between income and spending stays painfully small.
We need spending limits that protect our goals before lifestyle pressure takes over. A useful rule is to automate savings and investments immediately after income arrives, then spend from what remains. This flips the habit from “save what is left” to “spend what is left after we pay our future first.”
Ignoring Expert Guidance Can Make Small Mistakes Expensive
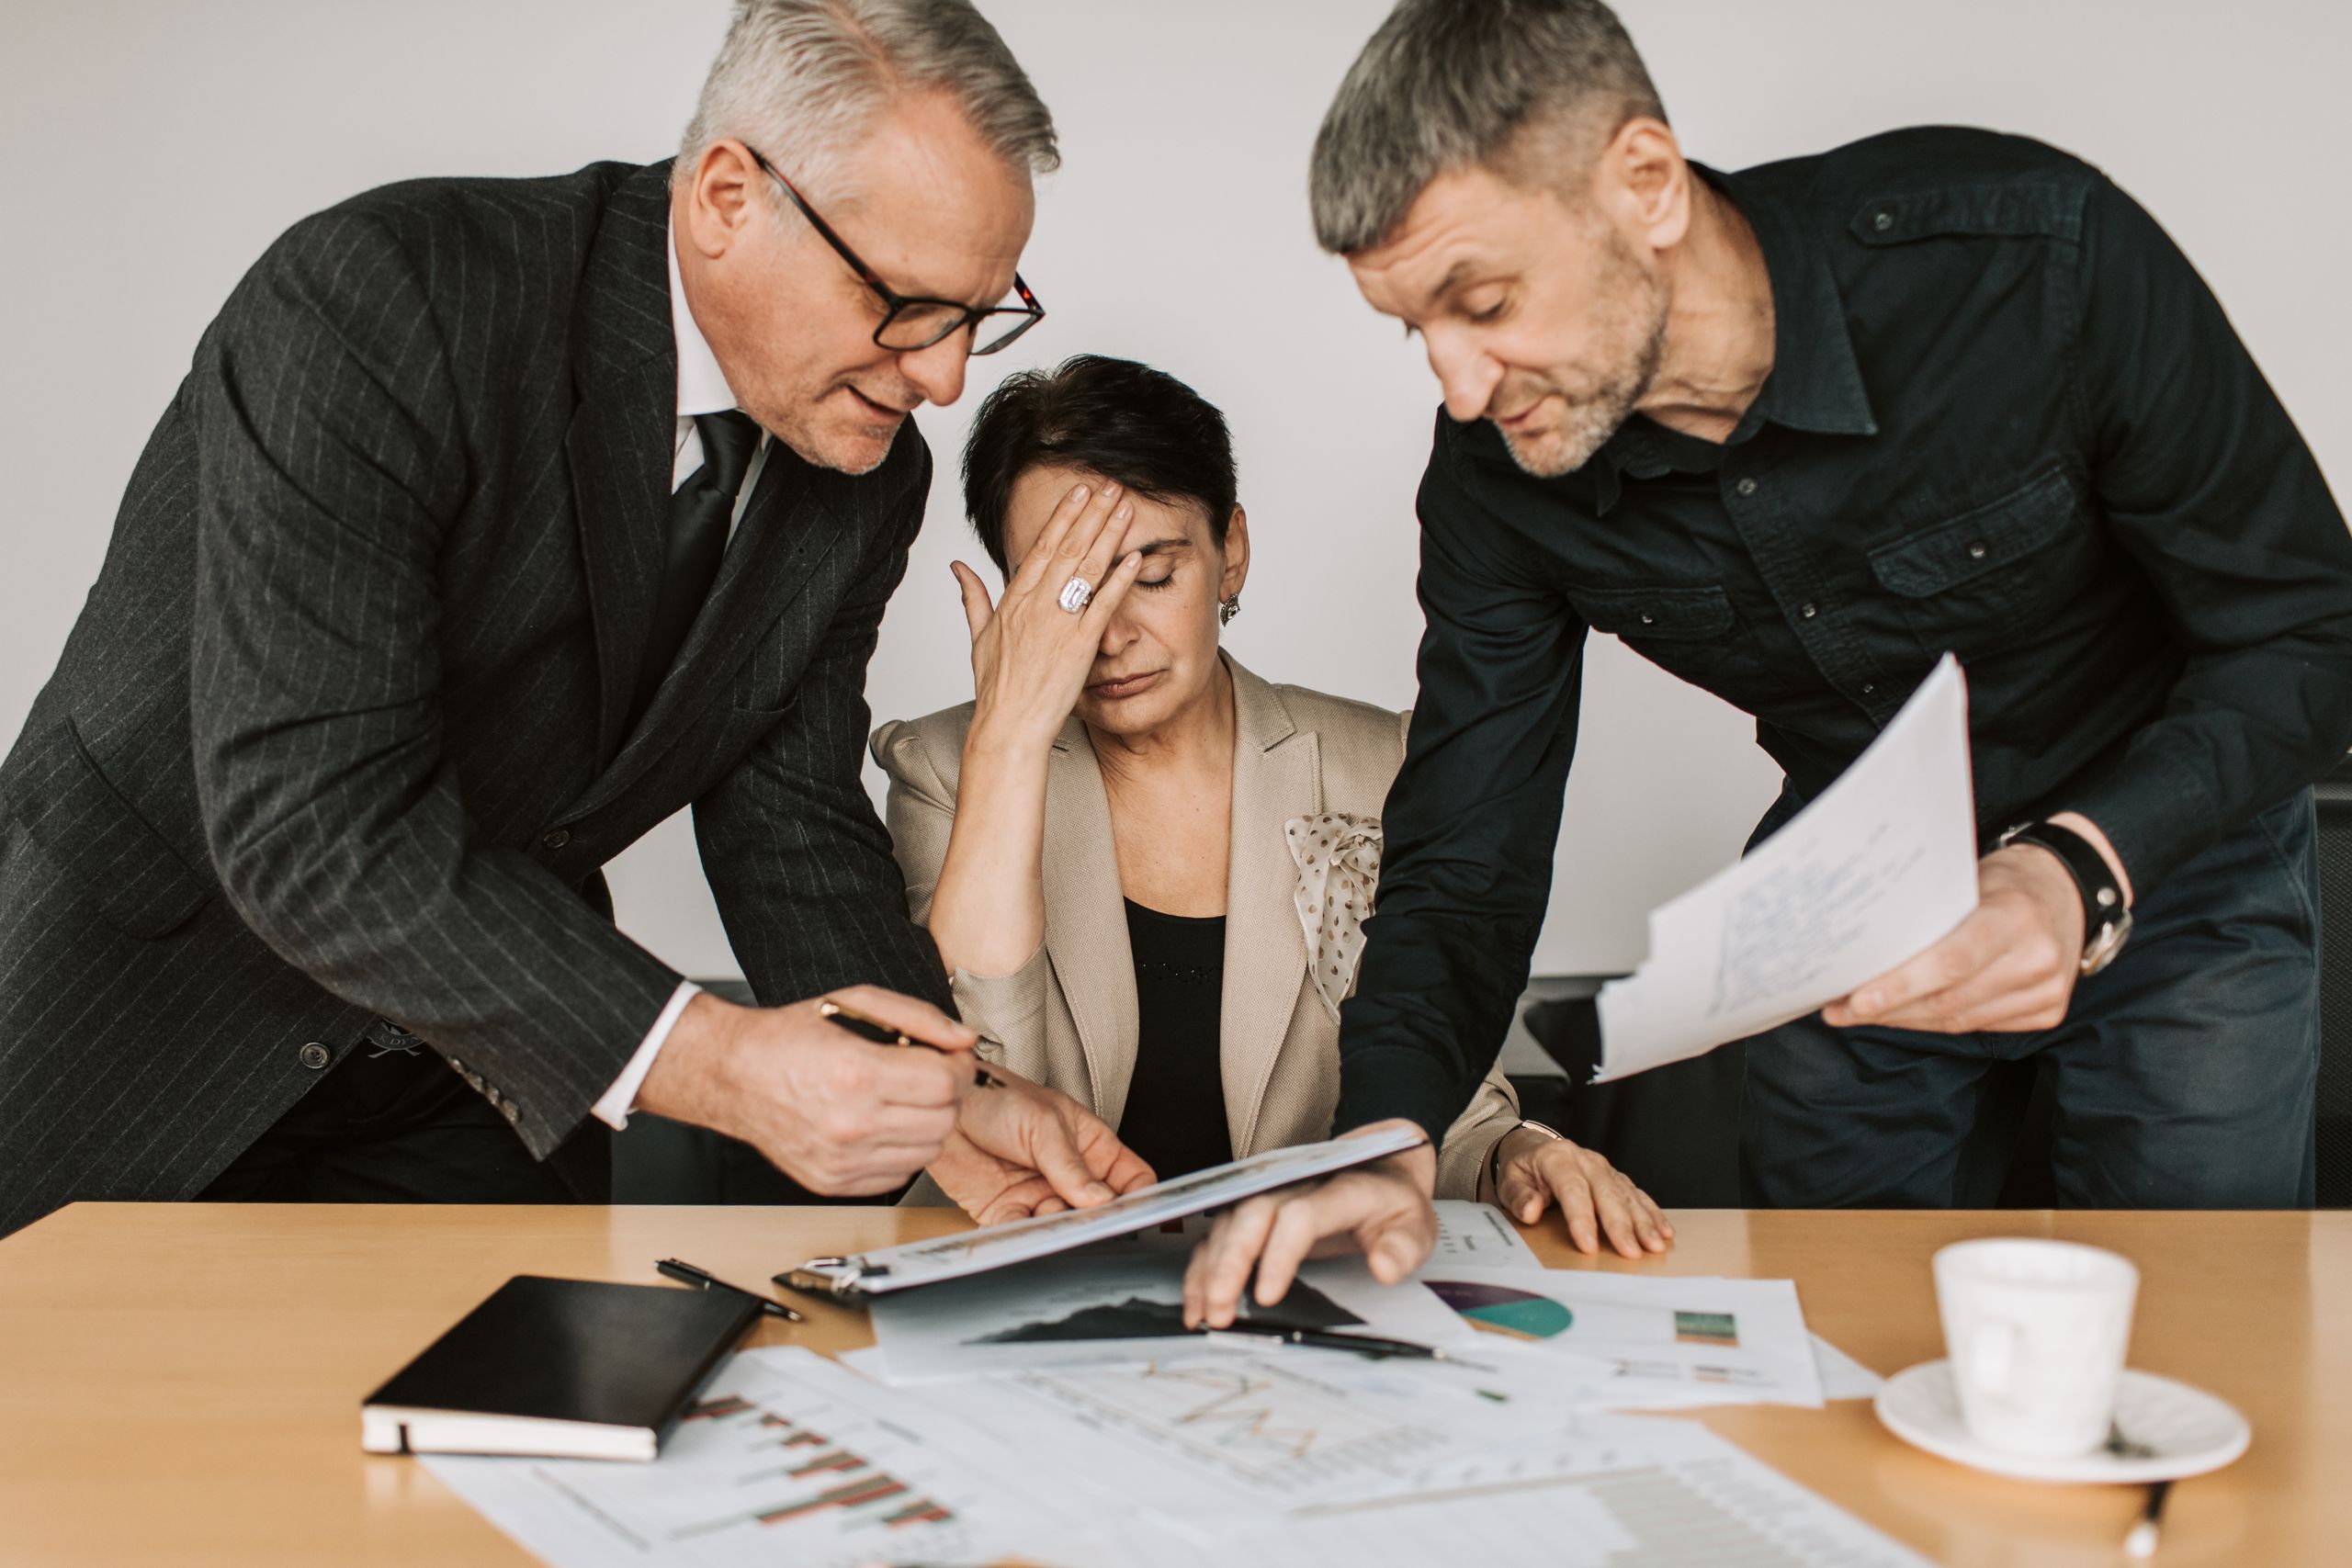
Financial confusion is expensive when it leads to delay, fear, or random decisions. Many people avoid asking questions because they feel they should already know everything about money. That silence can lead to unsuitable investments, missed retirement contributions, weak insurance choices, avoidable tax mistakes, and debt strategies that cost more than necessary.
Expert guidance does not mean surrendering control. It means using better information before making decisions that affect years of income. We should still understand fees, risks, timelines, and alternatives, but the right professional advice can help us avoid costly blind spots.
How We Fix Money That Is Not Growing
We start by tracking the last 30 days of spending. This shows the truth faster than guessing. Once we see where money actually went, we can cut the expenses that bring the least value and redirect that cash toward debt reduction, savings, or investments.
Next, we separate short-term money from long-term money. Emergency cash should stay accessible, but money for retirement or future wealth needs a growth plan. For 2026, workers can contribute up to $24,500 to many 401(k), 403(b), and similar workplace retirement plans, giving eligible savers more room to build long-term wealth.
Finally, we built automation into the system. Automatic transfers remove emotion from saving and investing. When money moves before we can spend it, discipline becomes easier, and growth becomes more consistent.
Final Takeaway
Money grows when we stop letting chance manage it. A strong plan, clear goals, controlled debt, smarter savings, realistic investing, and disciplined spending can turn ordinary income into real progress. The secret is not earning endlessly more; it is making the money we already earn behave with purpose.