America’s housing market is finally showing cracks, and the pain is not landing evenly. Some homeowners are still sitting on huge gains, but others are discovering that the pandemic price boom came with a nasty aftertaste: higher insurance bills, higher mortgage payments, higher taxes, and buyers who are no longer willing to fight over every listing.
This is not a nationwide housing collapse. It is more uncomfortable than that. It is a regional reset, and it is hitting the places that became too expensive too fast. ATTOM reported that median sale prices fell year over year in 39 of 129 large U.S. metro areas in the first quarter of 2026, with the biggest drops concentrated in Florida, Texas, North Carolina, and California.
Cape Coral, Florida: The Dream Home Market Is Getting a Harsh Reality Check

Cape Coral is the clearest warning sign in America’s housing slowdown. ATTOM found that Cape Coral posted the steepest year-over-year median sale price decline among major metros, falling 9% in the first quarter of 2026.
That drop matters because Cape Coral was once a pandemic era magnet for people chasing sunshine, space, retirement comfort, and waterfront living. Now the cost of staying in Florida has become harder to ignore.
Insurance, flood risk, repair costs, and higher borrowing costs have made the dream feel expensive even after home prices cool. For many Americans, that is the real shock. A lower asking price does not help much when the monthly cost still punches like a heavyweight.
Durham, North Carolina: A Popular Southern Market Is Losing Some Shine
Durham’s housing story feels especially painful because it is not a weak city. It has universities, hospitals, research jobs, and a strong quality-of-life pitch. Yet ATTOM reported that Durham’s median sale price dropped 8.7% year over year, making it one of the biggest decliners in the country.
That tells us something many buyers already feel in their bones. A city can be desirable and still overpriced. During the pandemic boom, many households moved into Southern markets expecting more space for less money. Then prices rose, mortgage rates stayed elevated, and the math stopped feeling friendly. Durham is now showing what happens when a “good market” still runs into affordability fatigue.
Austin, Texas: The Tech-Boom Darling Is No Longer Untouchable
Austin became one of the great symbols of pandemic migration. Tech workers moved in, investors showed up, builders rushed to meet demand, and prices soared. That glow has faded. ATTOM reported that Austin’s median sale price fell 7.2% year over year in the first quarter of 2026.
For American homeowners, Austin is a cautionary tale. A hot city can cool quickly when buyers start doing the full monthly-payment math. Realtor.com’s April 2026 report showed that Austin had one of the sharpest declines in median list price per square foot among major metros, down 7.7% year over year. The message is blunt: even trendy markets can stumble when homes stop feeling affordable.
San Francisco, California: Even Wealthy Buyers Are Pushing Back
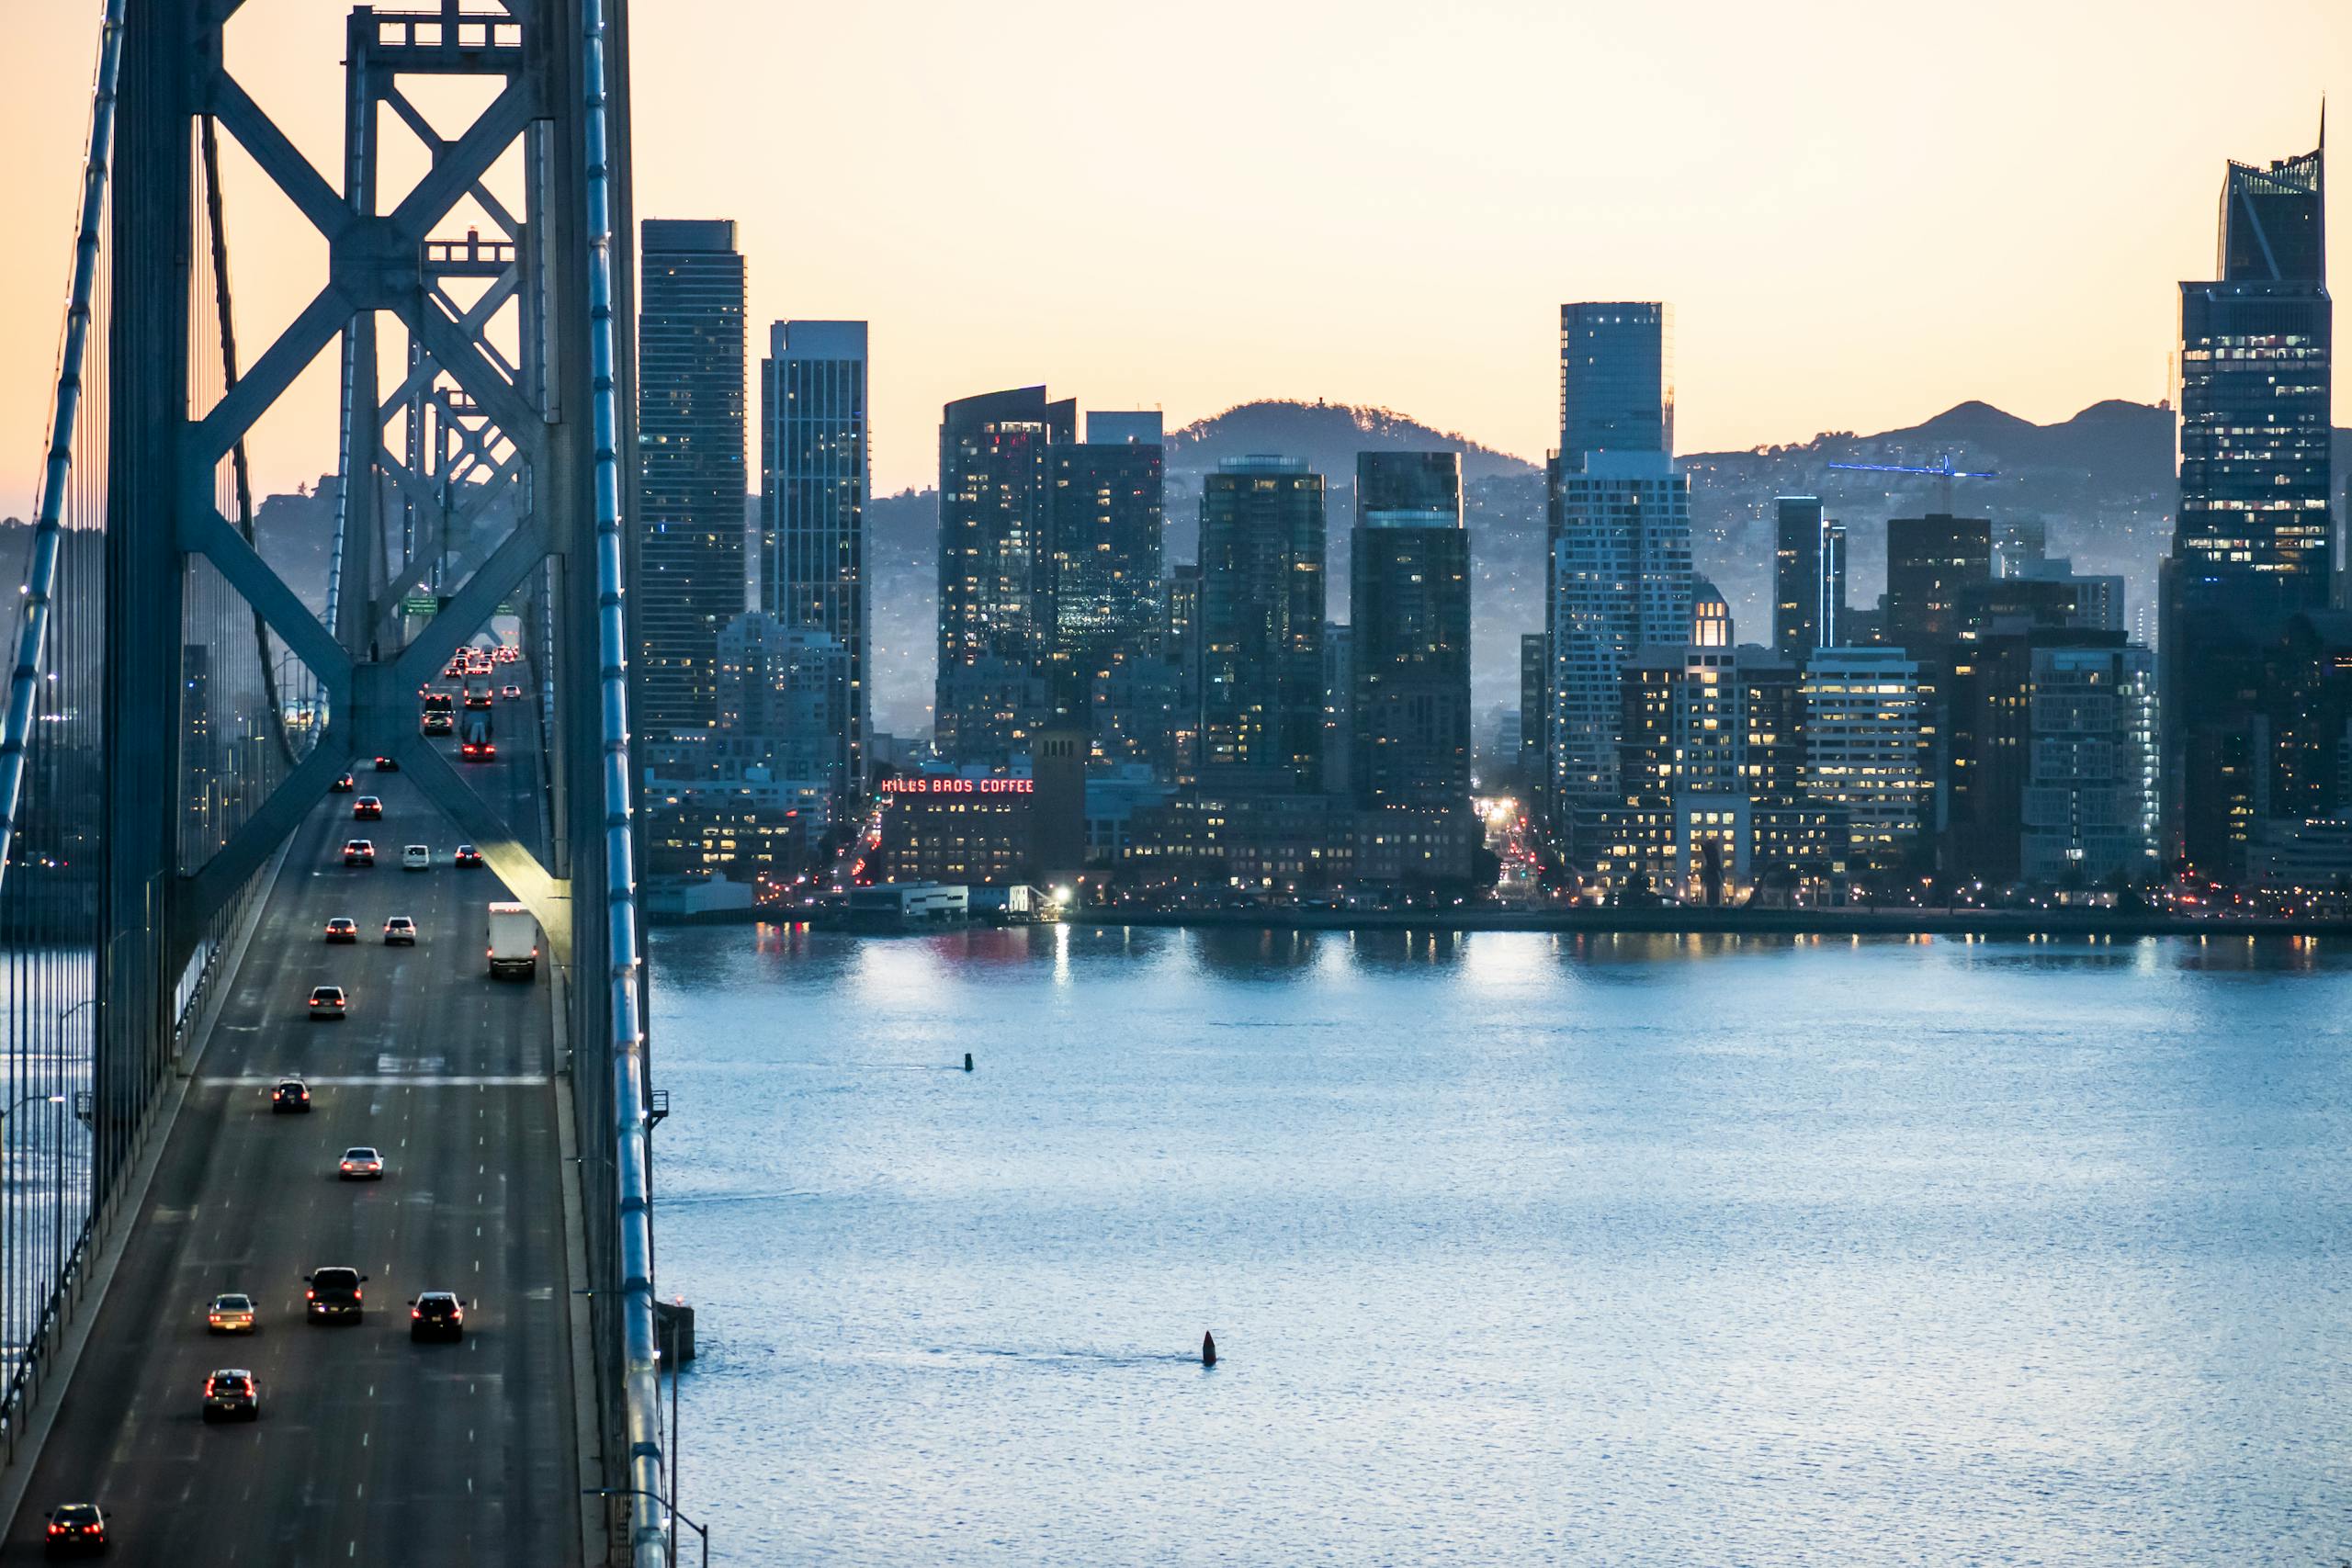
San Francisco’s housing market has always lived in another financial universe, but even luxury-leaning markets have limits. ATTOM reported that San Francisco’s median sale price fell 7.2% year over year in early 2026, tying Austin and Ocala among the steepest major-market declines.
That does not mean San Francisco suddenly became affordable. It means buyers at the top end are also asking harder questions. Is the commute worth it? Is the monthly payment worth it?
Is the old premium still justified when remote work, taxes, insurance, and lifestyle costs are all part of the decision? A price drop in San Francisco does not create a bargain for most families, but it does show that buyer resistance has reached even America’s most expensive housing circles.
Ocala, Florida: Smaller Florida Cities Are Feeling the Pressure Too
Ocala’s 7.2% median sale price drop shows that Florida’s housing pain is not limited to coastal luxury markets. This is important because smaller Florida cities attracted buyers who were priced out of Miami, Tampa, Orlando, and Naples. Many arrived looking for affordability, space, and a slower pace.
The problem is that the cheaper alternative became less cheap. Once mortgage rates, insurance, property taxes, and maintenance costs joined the bill, the savings became thinner. Florida’s housing slowdown now feels less like a coastal issue and more like a statewide affordability warning.
San Antonio, Texas: The “Affordable Texas” Promise Is Getting Weaker
San Antonio has long attracted buyers who wanted Texas living without Austin prices. That pitch still exists, but it is not as strong as it used to be. Realtor.com reported that San Antonio’s median list price per square foot fell 5.8% year over year in April 2026, one of the largest declines among major U.S. metros.
This is the part of the housing market that many Americans understand too well. A city can be cheaper than its neighbors and still feel expensive to regular households. Higher mortgage rates make even modest homes harder to carry. When wages cannot stretch far enough, buyers step back, sellers cut prices, and the market starts to lose its swagger.
Phoenix, Arizona: The Desert Boom Is Facing Buyer Fatigue
Phoenix became one of the most watched housing markets during the pandemic because it pulled in buyers from California and other high cost states. The city offered sunshine, newer homes, and relative value. Then prices climbed, mortgage payments ballooned, and the affordability advantage started shrinking.
Phoenix is part of the wider Sun Belt slowdown because the old demand story is no longer enough on its own. Buyers still like warm-weather markets, but they are more cautious when monthly payments remain high. Freddie Mac reported that the 30 year fixed mortgage rate averaged 6.51% as of May 21, 2026, which keeps pressure on buyers even in markets where prices soften.
Raleigh, North Carolina: A Strong Job Market Cannot Save Every Listing
Raleigh remains attractive, but its market is no longer immune to pressure. ATTOM reported that Raleigh was among the large metros with major annual declines in seller profit margins, a sign that the easy gains sellers enjoyed during the boom are getting squeezed.
This matters because Raleigh has many of the ingredients Americans usually associate with housing strength: jobs, schools, migration, and livability. Yet high prices and elevated rates can still slow the market. The lesson is clear. A strong local economy helps, but it does not erase affordability pain when buyers feel boxed in.
Seattle, Washington: High Prices Are Meeting Tired Buyers
Seattle’s cooling market reflects a broader West Coast problem. The region still has strong jobs and deep wealth, but homes are expensive, borrowing costs are high, and buyers are more selective. In markets like Seattle, even well paid households can feel squeezed when the payments, taxes, insurance, and maintenance all stack together.
The national inventory picture also gives buyers more breathing room. Realtor.com reported that active listings reached 1,002,935 in April 2026, up 4.6% from a year earlier, while homes spent a median of 51.5 days on the market. That extra time matters. It allows buyers to compare, negotiate, and walk away from listings that feel overpriced.
Denver, Colorado: The Mountain Lifestyle Premium Is Under Stress
Denver’s housing market has benefited for years from lifestyle demand, outdoor appeal, and steady migration. But high prices have made the city harder for ordinary buyers to absorb. When rates stay elevated, even a small price cut may not be enough to make a home feel affordable.
This is where the American housing problem feels especially frustrating. Buyers may see headlines about prices falling, then discover the monthly payment still looks brutal.
NAR reported that April 2026 existing-home sales stood at a seasonally adjusted annual rate of 4.02 million, with a national median sales price of $417,800 and 4.4 months of inventory. In plain English, homes are moving slowly, but they are still not cheap.
Conclusion
The most relatable housing story in America right now is not that prices are crashing everywhere. It is that many people still feel trapped even as prices start to fall.
Buyers see discounts, but mortgage rates keep monthly payments painful. Sellers see cooling demand, but many still need high prices to protect the equity they counted on.
The cities seeing the biggest price drops are warning signs for the wider market. Cape Coral, Austin, Durham, San Francisco, Ocala, San Antonio, Phoenix, Raleigh, Seattle, and Denver all show what happens when pandemic hype meets real household math.
The American housing market is no longer running on blind urgency. Buyers are slower, sellers are nervous, and the old promise that home prices only move one way is starting to look painfully outdated.